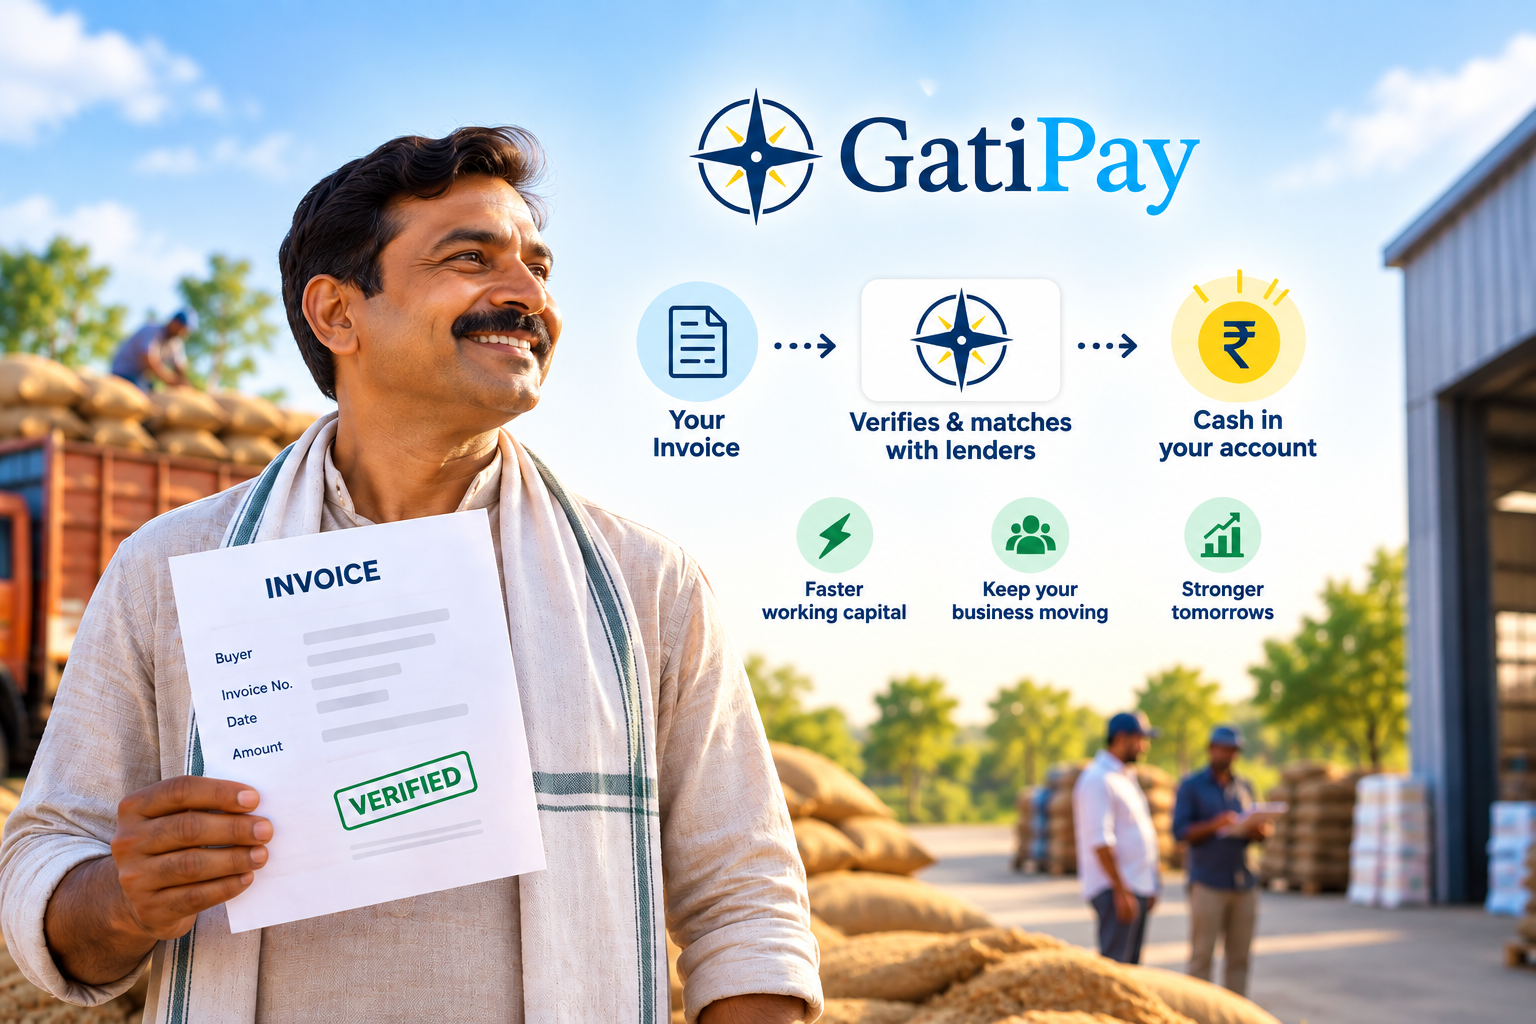
Invoice discounting (also called bill discounting in India, and searched as “invoice financing”) lets a business draw cash against an invoice it’s already issued, instead of waiting for a buyer’s 30–90-day payment term. GatiPay’s Invoice Discounting product matches a verified invoice directly with a lender from its partner network, using AI-powered underwriting built on real trade data rather than just balance sheets.
A commodity trader ships two truckloads of wheat to a processing mill. The mill accepts delivery and sets a 60-day payment schedule, standard practice. The trader has done everything right, but the next harvest cycle doesn’t wait 60 days, nor does the labor or the transporter. The money is earned. It’s just trapped inside someone else’s payables queue.
This is the problem invoice discounting solves, and for India’s agri-traders and MSME suppliers, it recurs every cycle.
SIDBI puts the MSME sector’s addressable credit gap at roughly ₹30 lakh crore. Bank credit to MSMEs grew 14.7% in FY2025, well ahead of overall bank credit growth of 11%, a sector expanding fast but still visibly underserved. MSMEs employ 30.16 crore people across 6.90 crore enterprises as of 30 September 2025, according to the Ministry of MSME. Separately, the Economic Survey 2025–26 estimates that roughly ₹8.1 lakh crore of MSME money sits locked in delayed payments.
The constraint isn’t a shortage of good businesses. It’s a shortage of fast, receivables-based capital.
Invoice discounting borrows against a specific invoice: the invoice itself is the security, not property or machinery. Whether the financier also has recourse to you if your buyer defaults depends on how the facility is structured, and that is the single most important term to establish before you sign.
| Feature | Invoice Discounting | Invoice Factoring | TReDS |
| Who collects from the buyer? | Usually the business itself | Usually the financing company | Settlement is routed through the platform |
| Does the buyer know? | Often confidential | Usually disclosed | Buyer participates on the platform |
| Recourse | Depends on the lending partner and facility | Depends on the facility | Typically without recourse to the MSME seller |
| Who is it for? | Businesses with eligible, verifiable invoices | Businesses assigning receivables | MSMEs selling to eligible buyers through the platform |
| RBI regulated? | Depends on lender and structure | Depends on financier and structure | Yes, TReDS is RBI regulated |
| Typical tenure | Usually tied to invoice payment terms | Usually tied to the receivables cycle | Usually short-term, tied to the accepted receivable |
TReDS (Trade Receivables Discounting System) is India’s RBI-regulated public exchange for this, and it just had its biggest overhaul in a decade.
On 23 June 2026, the RBI issued the RBI/DPSS/2026-27/406, consolidating the TReDS framework. The changes include easier onboarding, while platforms must still validate MSME status and ensure funds reach the seller’s own bank account. The Directions also permit guarantee support from any Government of India-notified credit guarantee fund trust and require every receivable assignment to be registered with CERSAI so the same invoice cannot be financed twice. Financiers can re-discount factoring units to other financiers, and insurance companies are formally recognised participants, with the premium not passed on to the MSME seller.
A 30 June 2026 notification also made TReDS mandatory as the settlement platform for CPSE purchases from MSMEs, with CGTMSE credit guarantee support for invoice discounting on the platform. The Budget also linked GeM to TReDS and opened the door to TReDS receivables being issued as asset-backed securities. Read the official RBI TReDS Directions for the full regulatory framework.
For an agri trader, the gap between buying stock and getting paid can be the difference between completing the next trade and sitting it out. A trader may buy wheat, rice, pulses, spices or other commodities, move them to a processor or institutional buyer, and then wait 30, 60 or 90 days for the invoice to be paid. The invoice is valid and the sale is complete, but the cash is not available for the next procurement cycle.
That is where invoice discounting for agri traders can become useful. Instead of taking a fresh loan against the business as a whole, the trader can seek financing against a specific, verifiable invoice. The financier advances a portion of the invoice value, less the applicable discount or fee, and the invoice is settled when the buyer pays.
Consider a trader who supplies ₹20 lakh of wheat to a processing company on 60-day terms. If the financier offers an advance of ₹19 lakh after applying its discount, the trader gets most of the receivable upfront and can use that money to procure the next lot, pay transporters, meet labour costs or bridge the next procurement cycle. The exact advance, fee and repayment structure depend on the lender and facility.
The same logic can matter for FPOs. Working capital for FPOs is often tied up after produce is aggregated and sold to a larger buyer. If the buyer’s payment comes later, financing against an eligible receivable can help the FPO keep procurement and member payments moving without waiting for the entire receivable cycle to close.
This is also why commodity trade finance in India increasingly needs to look beyond static balance-sheet strength. A business may have strong transaction history, repeat buyers and predictable trade flows even when its formal financial statements do not fully capture the speed of its operating cycle. Receivables-based finance can bring that operating history into the credit decision. For a broader view of how trade markets are being organised, see GatiPay’s related post on India’s scrap markets.
GatiPay is not a TReDS platform. It runs a private matching layer connecting MSMEs to its own lender network, so everything below sits alongside TReDS rather than on it.
GatiPay’s Invoice Discounting product is described on GatiPay’s website, which currently presents invoice discounting as early payments against verified B2B invoices.
GatiPay runs its own matching layer between MSMEs and a network of 120+ banks and NBFCs. Its underwriting looks at what a business has actually done, including verified trade history and transaction patterns, rather than just what it owns on paper. That matters most for agri-traders, FPOs and processors whose creditworthiness often appears in their ledgers long before it appears on a formal balance sheet.
Cash against an invoice you’ve already raised, instead of waiting for your buyer’s payment term to run its course.
No. A loan looks at your overall financials; discounting is assessed against one verifiable invoice and settles when that invoice is paid.
In discounting, you usually keep managing collections yourself. In factoring, the financier often takes that over, and the buyer usually knows.
In Indian usage the two terms are used more or less interchangeably for financing against an invoice you have already raised. Strictly, bill discounting refers to financing against a bill of exchange, but in practice most Indian lenders and borrowers mean the same product.
You are not pledging property or machinery; the invoice itself is what gets financed. Establish two things in writing before you sign: whether the facility is with or without recourse (with recourse, you repay the financier if your buyer does not pay), and whether a personal guarantee is required.
A discount or fee is deducted from the invoice value, varying by lender, buyer credit quality and invoice tenure. Always compare the effective cost to what waiting for payment would cost you.
Its engine evaluates transaction history, business performance and trade-specific risk, screening every profile against a lender’s credit policy before presenting it.
There is no single standard rate. The cost depends on the lender, buyer credit quality, invoice tenure, transaction risk and the structure of the facility. Compare the total effective cost, not only the headline rate.
Invoice discounting is generally structured around the receivable rather than property or machinery. However, collateral, guarantees and recourse can vary by lender and facility, so confirm the exact security and guarantee requirements in writing.
Exporters may use receivables-based finance to bridge the period between shipment, invoicing and payment. Eligibility and structure depend on the export transaction, buyer, documentation, currency and the lender’s policy.
If unpaid invoices are the reason your business feels stretched despite a healthy order book, that’s the exact gap invoice discounting is built to close. GatiPay’s borrower team can walk you through whether your receivables qualify.